02 / Research & methodology

Selected Research & Methodology

Research on market states, signal formation, portfolio decision systems, macro context and AI-enabled research workflows. These studies illustrate the research frameworks used inside Yiheng Quant Tech.

R / 01

Multi-Source Market Intelligence with LLM
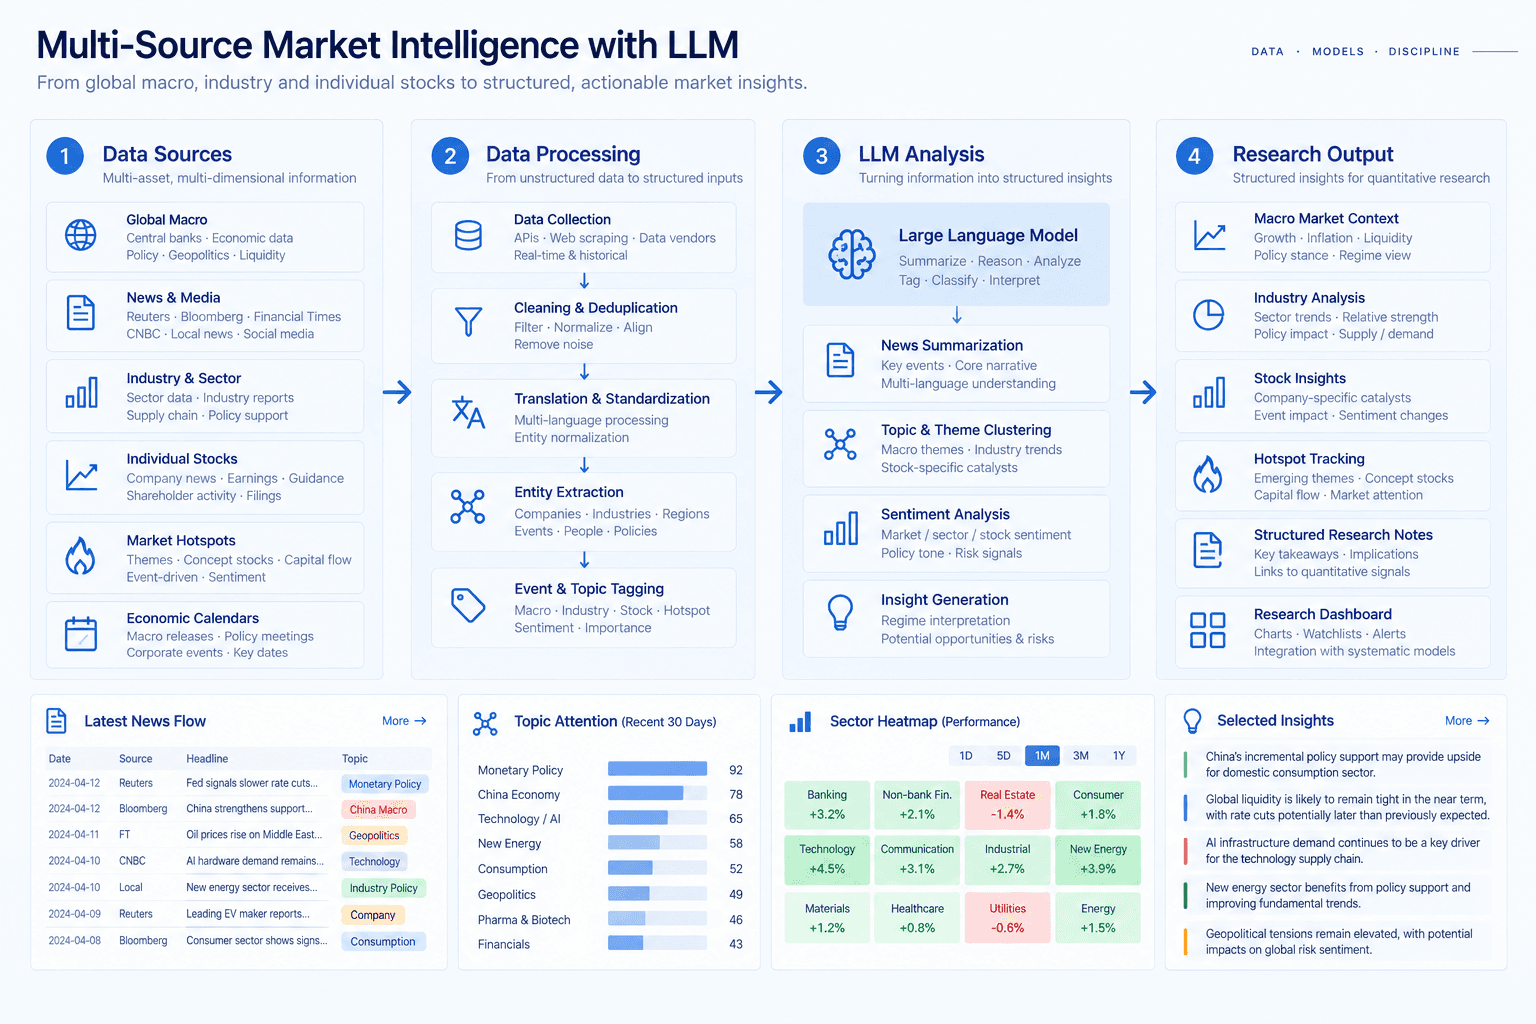
Multi-source market intelligence workflow: macro, industry, stock news, hotspots and economic calendars feed data processing, LLM analysis and structured research output.

A multi-source research workflow combining global macro, industry and sector information, individual-stock news, market hotspots and economic calendars, with LLM-assisted summarization, classification, theme extraction and structured research output.

R / 02

Compression → Expansion

Research into volatility compression, volume contraction and breakout / expansion setups.

R / 03

Position State Machine Validation

A framework for analyzing position-state transitions and position lifecycle decisions.

R / 04

Market Regime Classification

Risk-OnNeutralRisk-Off0.80.91.01.11.21.31.4CSI 300Regime score · trailing observations0501002023-092025-012026-012026-09

Macro-aware market-regime research combining liquidity, growth, policy, volatility and cross-asset context.

R / 05

Cumulative Performance

Research StrategyCSI 300
0.80.91.01.11.21.31.41.51.61.71.82023-092025-012026-012026-09

Strategy-versus-benchmark cumulative-return comparison.

R / 06

Drawdown Comparison

Research StrategyCSI 300
-20%-10%0%2023-092025-012026-012026-09

Underwater / drawdown comparison emphasizing downside behavior and risk control.